0
The Week That Was – Middle East, Oil and the Big Macro Picture
Gold and silver had a proper shake-up this week. Prices swung hard on news from the Middle East, oil jumping everywhere, and fresh worries about inflation and interest rates. By Friday, gold settled in the low-to-mid A$7,000s per ounce. Silver hung around A$120/oz after some wild days. But this wasn’t just random noise – it was macroeconomics doing its thing. Here’s the full story, Aussie-style.
Middle East Sparks the Fire – Oil Jumps, Everyone Feels It
The headlines came thick and fast from the Middle East. Strikes are flying both ways, hitting oil facilities and blocking key shipping lanes. That narrow Strait of Hormuz, where most of the world’s oil tankers squeeze through, turned into ground zero. One wrong move there, and the global oil supply gets choked.
Oil prices rocketed. Traders priced in weeks of disruption, not just a quick drama. Brent crude spiked hard, pushing past levels we haven’t seen in ages. That means higher petrol prices, more expensive transport, and rising energy costs for businesses.
Here’s the macro chain reaction:
- Higher oil prices = higher inflation. Fuel costs flow straight into CPI. Food, freight, manufacturing – everything gets pricier. Central banks hate that when they’re trying to cool things down.
- Growth takes a hit. Businesses spend more on energy, less on hiring or expanding. Consumers tighten their belts when petrol eats into their budget.
- Safe-haven rush. Shaky world? People pile into gold. It’s not tied to any one currency or government. Silver rides the wave but with extra bounce.
Gold jumped on the bad news days. Dips got snapped up fast. Silver did the same but with bigger kicks, up 8-10% one session, back half that the next.
Gold’s Steady Climb – Chart Tells the Tale
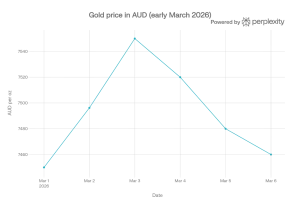
Gold didn’t crash through new highs this week, but it held a lofty perch. Started Monday around A$7,450/oz, nudged up to A$7,550 midweek as oil fears peaked, then eased to A$7,460 by Friday. Daily swings hit 3-4%, but the base stayed rock solid.
That’s gold in crisis mode – fear pushes it higher, calmer news pulls back a bit, but buyers step in before it tests real support. Over the past year, it’s doubled from A$3,500s and this week just confirmed the uptrend.
[Gold price chart in AUD – early March 2026]
Silver’s Rollercoaster – Industrial Kicks In
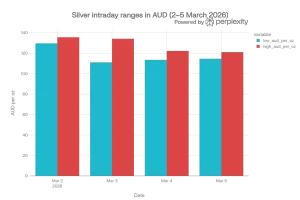
Silver told a louder story. It thrashed between A$110 and A$135/oz most days – proper volatility. Check the daily ranges:
- Monday: Low A$129, high A$135
- Tuesday: Plunged to A$111, clawed back to A$134
- Wednesday-Thursday: A$113-122 band, still swinging 5-10% daily
Why so jumpy? Silver’s got a dual personality. Half the demand is investors treating it like gold. The other half is factories – solar panels, electronics, EVs. Oil shocks help the safe-haven side, but if growth slows (higher costs crimp spending), industrial buyers pull back. Result: wilder swings than gold.
[Silver daily high-low chart in AUD]
The Macro Backdrop – Rates, Dollars and Central Banks
Peel back the headlines, and bigger forces were at play. Global growth slowed – think softer GDP prints from major economies. Inflation? Still sticky, especially core measures that central banks watch like hawks. That combo means rate cuts aren’t coming fast.
- RBA holding steady, while the Fed and ECB say wait. No rate cuts while inflation sticks.
- Dollar dance: Firmer greenback usually knocks gold, but not this week. Safe-haven trumped currency.
- Central bank binge: Over 1,000 tonnes of gold bought yearly since 2022. BRICS nations swapping bonds for bullion. That’s a rock-solid floor.
Even as shares ground higher, metals priced the tension. Not panic – smart hedging.
Tying It All Together – Inflation, Policy and Your Wallet
Zoom out, and this week spotlights the macro bind:
- Oil shock revives inflation dragon. Just when CPI was taming, energy blew it wide open. Central banks are stuck between squashing prices (higher rates) and propping up growth (cuts).
- Policy paralysis. Growth soft, inflation hot – textbook stagflation lite. Gold thrives here; no yield but no counterparty risk.
- Aussie angle. Higher import costs hit us hard – net importer of oil. RBA watches, but global forces dominate.
Prices reflect that tension. Gold’s A$7,000s floor ain’t cheap, but it’s earned. Silver’s A$120 wobble suits traders chasing the beta.
What’s Ahead?
No crystal ball, but three macro paths are visible at this point:
- Oil stays high, conflict simmers – Inflation bites, rates on hold, metals grind higher.
- De-escalation miracle – Oil eases, growth rebounds, metals chop but hold gains.
- Data shock – Weaker numbers force cuts (bullish metals); hotter CPI delays them (choppy).
Expect bumps. High prices, high volume – classic.